Car Leasing Companies in Dubai: How to Choose One, and What to Ask Before You Sign
Four different products hide behind the words "car leasing company". Work out which one you are being offered, then get the cost, the ownership and the exit terms in writing before you pay anything.
What is the best car leasing company in Dubai?
There is no single best car leasing company in Dubai, because the phrase covers four different products: rental-style leases you hand back, bank or dealer car loans, lease-to-own contracts and brokers without cars. Choose the product first, then the company: how long you need the car, which documents you can show and whether you want to own it.
We are a lease-to-own company, so read this with that in mind; we also say where another product beats ours. Car figures are from our live fleet on 1 November 2026 and change with it.
What our customers ask before they commit. Between 26 September and 1 November 2026, 59 customers asked us questions in chat that needed a manager's answer rather than a standard reply. More than half of them asked about at least one of three things: how the contract ends, including early settlement and what is due at the end (about 17 people); the full cost and the annual payment (about 15); and the car's own history, such as GCC specification, accidents and odometer (about 11). Those are where contracts differ most.
What kinds of car leasing company are there in Dubai?
1. Rental-style lease (operating lease or long-term rental)
- Who owns the car: the leasing company, during the contract and after it
- What you pay: a monthly that usually bundles insurance, registration, servicing and a replacement car, often with a deposit
- What many ask for: passport, visa, Emirates ID, licence and often a salary certificate, bank statements or consent to an AECB credit report
- At the end: you hand the car back after a return inspection
2. Bank or dealer car loan
- Who owns the car: you, with the bank's mortgage on the registration until the loan is repaid
- What you pay: at least 20% down, because Central Bank rules cap a car loan at 80% of the car's value and 60 months; insurance and registration are yours every year
- What banks ask for: salary certificate, bank statements and an AECB report, with all your loan repayments within half of your income
3. Lease-to-own, also sold as rent-to-own
- Who owns the car: the leasing company during the term, you at the end
- What you pay: a fixed monthly and, with us, one annual payment for insurance and registration; some companies add a large final payment, so ask
- What they ask for: anything from a full bank-style file to two documents
4. Brokers and listing sites without their own cars
- Who owns the car: someone else, often named late in the process
- What to check: who signs the contract with you, and whose name is on the registration
Some dealers and rental firms now add a lease-to-own option to an all-inclusive monthly: ask for its term, total and any amount due at the end, in writing.
Who owns the car during the contract, and at the end?
In the UAE a car is registered in its owner's name, and the registration card, the mulkiya, shows who that is. A car cannot be registered without insurance from an authorised insurer, and a bank's mortgage over a car is recorded against its registration. So ask about the mulkiya of the exact car you are offered.
- Bank loan: the mulkiya is in your name with the bank's mortgage on it, and you cannot sell cleanly until the bank releases it
- Rental-style lease: the mulkiya stays in the company's name from start to finish
- Lease-to-own: the mulkiya stays with the leasing side for the term and moves to you after the last payment. Check that the contract says so and who pays for the transfer, and that the car carries no mortgage from the company's own bank that would block it
With us, the car is registered to the leasing company during the term and insured and registered through the annual payment. After your last payment we start the RTA transfer and handle the paperwork and fees; our FAQ puts it at 5–7 business days, ending with a registration card in your name and no lien. Settle early and the transfer starts once the contract is paid in full.
Is the car really in their fleet?
Some sites list cars they do not own, and we have seen it first-hand. In September 2026 we found a website that had copied our entire catalogue: all 41 cars we listed at the time, monthly payments matching ours to the dirham, our photographs re-uploaded as its own. It had no cars at all.
Ten-minute checks:
- Ask for the VIN and check that model, year and specification match the listing
- See the car before you pay anything, and read the odometer yourself
- Another company's watermark on the photos, or the same car at the same price on several sites, means you should ask who owns it
- Ask whether it is GCC specification; imports are legal, but their history is harder to verify
On our side, every car in our fleet has passed a 150-point inspection at our partner workshop, including VIN and odometer checks, paint-depth readings and a diagnostic scan, and we prefer GCC specification. You can see the car by appointment, or we bring it to you anywhere in Dubai.
What is the full cost, in writing?
A monthly figure alone tells you little. Ask for these lines in writing, for the exact car, down payment and term:
- The car price the contract uses, and whether VAT is included
- The down payment, and whether it counts as the first payment
- How many monthly payments follow, and the amount of each
- Every recurring charge outside the monthly
- Any final payment due at the end
- The total if you keep the car to the end
- What it costs to end early at month 6, 12 or 24
How we calculated two of our own cars. Standard plans with no final payment, from our live fleet on 1 November 2026. The monthly is fixed on the day you sign and nothing compounds. The down payment counts as payment number one, so a 36-month plan has 35 monthly payments after it. The annual payment is 5% of the car's price, minimum AED 8,000.
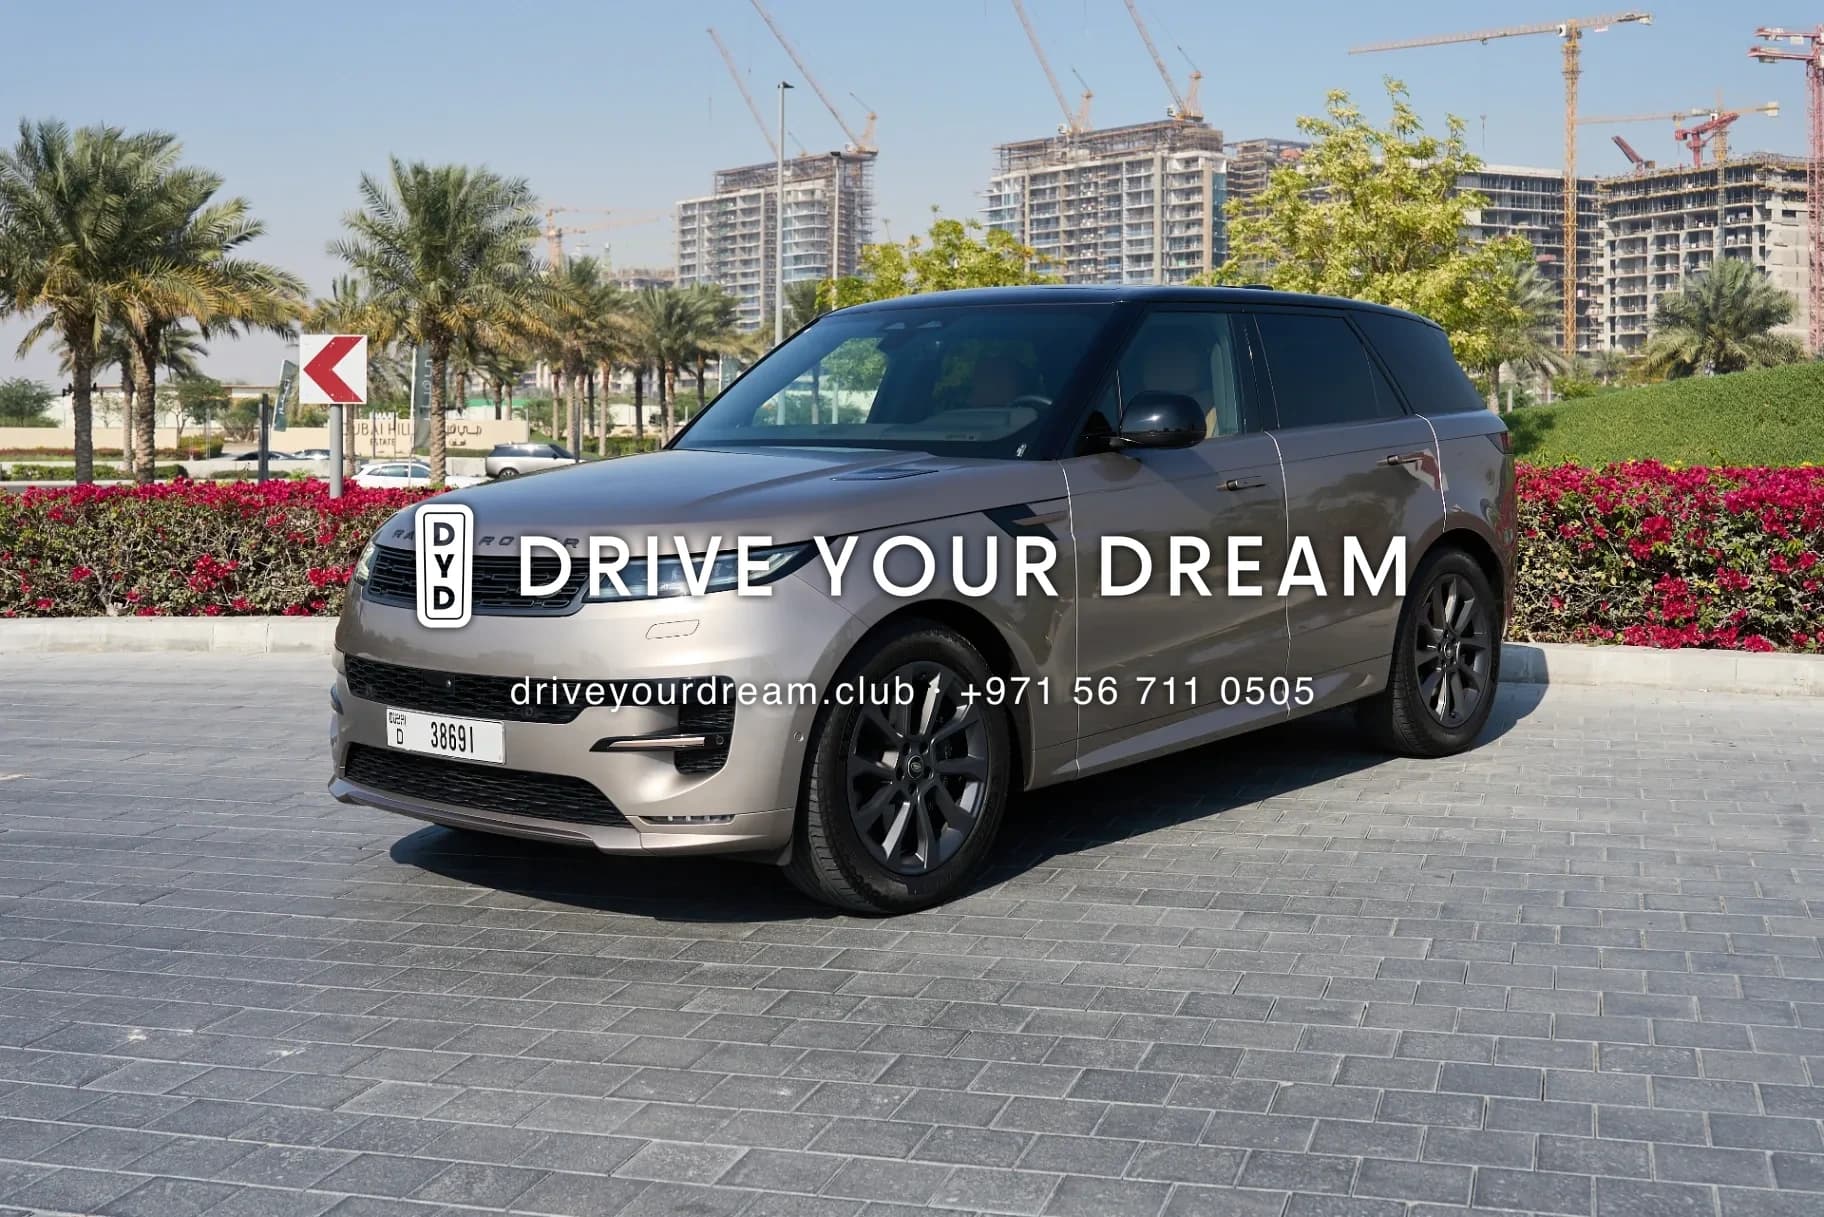
Range Rover Sport 2023, AED 315,000
- 20% down, 36 months: AED 78,750 on day one (AED 63,000 down plus the AED 15,750 annual payment), then 35 monthly payments of AED 12,384, with the annual payment again in years two and three. Total: AED 543,690
- No down payment, 24 months: AED 35,175 on day one (the first monthly of AED 19,425 plus the annual payment), then 23 more of AED 19,425. Total: AED 497,700
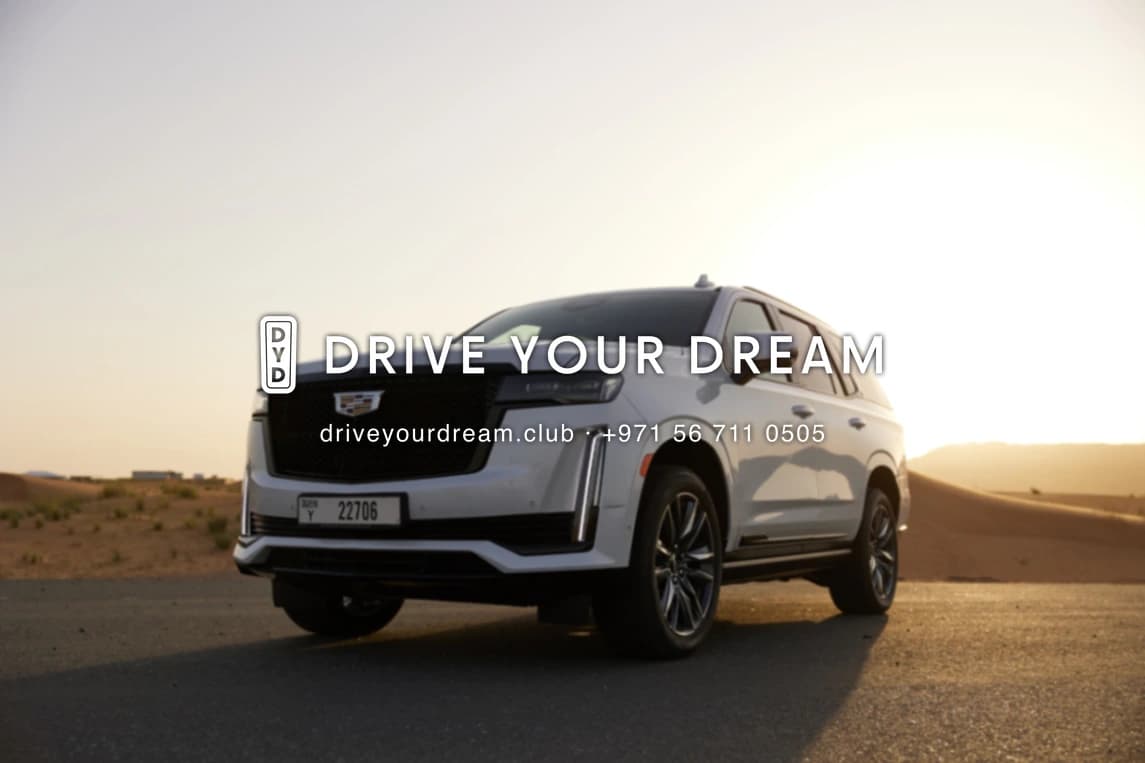
Cadillac Escalade 2023, AED 275,000
- 20% down, 36 months: AED 68,750 on day one (AED 55,000 plus AED 13,750), then 35 monthly payments of AED 10,811. Total: AED 474,635
- No down payment, 24 months: AED 30,708 on day one, then 23 more of AED 16,958. Total: AED 434,492
Same method, different terms: the Range Rover can start without a down payment on 12, 24 or 36 months, the Escalade on 12 or 24 only, with 36 months from 20% down. So always ask for the terms on the exact car. Some car pages show a lower headline monthly that assumes an optional final payment, offered on selected cars only; the figures above have none.
The two cars in these examples
Live from our fleet. Each card shows the car's lowest headline monthly, which can assume an optional final payment; the worked figures above are the standard plan with none. Insurance, RTA registration and admin come as one annual payment.
What does the annual payment cover, and what stays with you?
On a rental-style lease most running costs sit inside the monthly; on a bank loan all of them are yours. With us:
- The monthly covers the car itself; GPS tracking is fitted at no extra charge
- The annual payment, 5% of the price with a minimum of AED 8,000, covers comprehensive insurance from a UAE insurer, RTA registration, roadside assistance and our admin, renewed by us every year
- Yours to pay: fuel, Salik, parking and traffic fines, routine servicing (oil, tyres, brake pads) and kilometres over your allowance
Servicing is the honest difference: many rental-style leases include it and ours does not, so budget for it when you compare monthlies.
Mileage, travel outside the UAE and off-road: what is allowed?
Usage rules surface late, usually when a claim is declined, so ask for them before signing. Ours apply to every car:
- Mileage: 25,000 km a year, with 35,000 and 50,000 km packages at signing or mid-term. Extra kilometres cost AED 10 each, more than many rental-style leases charge, so take a package if you drive a lot
- Off-road, desert driving and track days: not permitted, because a normal UAE comprehensive policy excludes them
- Leaving the UAE: not permitted. A car you do not own outright needs a no-objection certificate from its legal owner to cross a border, and its insurance would have to extend abroad
- Towing: allowed with the right licence category if you tell us first; insurance may cost more
If a company says something is allowed, ask to see it in the contract and the policy.
What happens if you miss a payment, pay off early or your visa is cancelled?
- A missed payment. Ask for the grace period and what follows. With us: seven days' grace, after which the car can be immobilised remotely until the balance is paid. We always contact you first, and it is better to talk to us before a payment is missed
- Paying off early. Ending a rental-style lease early often costs part or all of the remaining rentals, so ask for the amount at months 6, 12 and 24. With us you can settle at any time with no early-settlement penalty, and the car transfers to your name once paid in full. Want to sell mid-term? Settle first, then it is yours to sell
- A cancelled visa or lost job. Ask what the contract says before you need it. With us the first step is a conversation: depending on the contract, you settle and keep the car, or hand it back and settle your position
No credit check car leasing companies: what do they check instead?
Banks and many rental-style lessors decide on paperwork: salary certificate, bank statements, time with your employer and your AECB report. If one is missing, the answer is often no.
We decide on two documents: your Emirates ID and your UAE driving licence. No salary certificate, bank statements, salary transfer, trade licence or AECB report. A decision usually comes within 24 hours, and the car can be with you in 1–3 business days. No credit check does not mean no decision: we read every application ourselves, and some are declined. You need to be at least 21 and hold a UAE residence visa.
A company applies with its trade licence, MOA, the signatory's Emirates ID and a licence for each driver; these identify the company, they are not proof of income. Be wary of anyone promising guaranteed acceptance, especially for a fee paid upfront.
Red flags: when to walk away from a car leasing company
- No trade licence you can find, or one for something unrelated to cars. Ask for the licence number and check it with the issuing authority; the federal National Economic Register lets you enquire about UAE business licences. Ours: Drive Your Dream L.L.C-FZ, UAE trade licence 2530871.01, covering used car trading and car rental. We are not a bank and do not lend money: we own the car and lease it to you
- Money requested before you have seen the car, the contract or a written total, or a request to pay into a personal account
- A monthly quoted without the term, the down payment, the yearly costs and any amount due at the end
- "Lease to own" in the advert, but a large final payment in the contract that you did not ask for
- No VIN, no viewing, and pressure to sign today without a copy of the contract to read
- A promise that the car can go off-road or to Oman with nothing in writing from the insurer: off-road use is a standard exclusion, and cover outside the UAE has to be written into the policy
12 questions to ask any car leasing company, with our answers
Get the answers in writing. Ours follow each question.
- 1. Whose name is on the registration? The leasing company's, for the whole term.
- 2. Does the car become mine at the end? Yes. We arrange the RTA transfer, usually within 5–7 business days.
- 3. Is anything due at the end? Not on our standard plan.
- 4. What does the monthly include? The car itself; GPS tracking is fitted at no extra charge.
- 5. What do I pay every year on top? 5% of the car's price, minimum AED 8,000, for insurance, registration, roadside assistance and admin.
- 6. How much cash on day one? About a quarter of the price at 20% down; selected cars can start without a down payment on some terms.
- 7. Can the monthly change? No. It is fixed on the day you sign.
- 8. What does early settlement cost? No penalty.
- 9. What if I pay late? Seven days' grace, then remote immobilisation until paid. We contact you first.
- 10. Mileage and extra kilometres? 25,000 km a year, packages to 50,000 km, AED 10 per extra km.
- 11. Which documents? Emirates ID and UAE driving licence; decision within 24 hours.
- 12. Can I see the car first? Yes, by appointment, or we bring it to you in Dubai.
When is lease-to-own with us the wrong choice?
- You qualify at a bank and have 20% down. A bank loan usually costs less over the full term
- You want a new car every year or two and to hand it back. A rental-style lease with servicing included often costs less per month
- You need a car for under a year. Rent one: a 12-month lease-to-own plan pays off the whole car in a year, so the monthly is high
- Your budget is far below our fleet. More than half of our cars cost over AED 7,000 a month at 20% down over 36 months, and most are premium SUVs and saloons, so a budget well below that leaves a narrow choice
- You drive over 50,000 km a year, or need to drive to Oman. Our packages stop at 50,000 km, and our cars are not permitted to leave the UAE
Where we are strong: two documents instead of a bank file, a decision within 24 hours, cars we can show you, two fixed payments, no early-settlement penalty and the car in your name at the end.
Not in our fleet? Bring Your Own
If you have found the car on the UAE market, our Bring Your Own programme can buy it and lease it to you: listings from AED 150,000, model year 2023 or newer (selected luxury cars from 2021 are considered individually), not a Chinese brand and not fully electric (hybrids are fine). Plans are priced on the listing plus 5% VAT, from 20% down over 12 or 24 months (36 months only case by case), with no final payment: the car is yours after the last monthly. An AED 150,000 listing works out from AED 8,108 a month over 24 months at 20% down, with AED 39,500 to start. Link to keys usually takes 5–7 business days, once the car passes our inspection.
How we checked these figures
Car figures come from our live fleet, calculator and published rules on 1 November 2026, and they change with the fleet: the car page always shows today's numbers. The customer-question figures are counts of manager notes in our chat records from 26 September to 1 November 2026, sorted by keyword, so treat them as approximate; no names or phone numbers were used. The bank, registration and licence rules quoted above were checked on 1 November 2026 against the official sources below.
Terms can change, and every plan is subject to DYD confirmation for the specific car and applicant. The contract you sign is what applies.
Sources
- Registering vehicles: inspection, insurance and mortgage rules, UAE Government portal (u.ae)
- Getting a car loan: at most 80% of the car's value, up to 60 months, repayments within half of salary, UAE Government portal (u.ae)
- Regulation No. 29/2011 regarding bank loans and other services offered to individual customers, Article (3) Car Loan and Article (7), published in the CBUAE Rulebook (rulebook.centralbank.ae), Central Bank of the UAE, 2011-03-23
- National Economic Register: enquire about UAE business licences, UAE Government portal (u.ae)
- Renew and amend vehicle ownership data (vehicle registration in Dubai), Roads and Transport Authority (RTA), Dubai
Frequently Asked Questions
What are the best car leasing companies in Dubai?
There is no single best one, because the name covers rental-style leases, bank or dealer car loans, lease-to-own contracts and brokers without cars. Pick the product that fits your plans, then compare companies on the written total, who owns the car and the cost of ending early.
Are there car leasing companies with no credit check in the UAE?
Yes. Some lease-to-own companies, including us, decide without an AECB report, because the company owns the car for the term. We ask for an Emirates ID and a UAE driving licence and give a decision within 24 hours. Some applications are still declined, and a promise of guaranteed acceptance for an upfront fee is a red flag.
Can I lease to own a car in the UAE without a bank?
Yes. On lease-to-own the leasing company buys the car and leases it to you, so no bank is involved. With us you pay a fixed monthly and one annual payment for insurance and registration, and the car transfers to your name after the last payment. If you qualify at a bank and have 20% down, a bank loan can cost less in total.
How can I check that a car leasing company in Dubai is legitimate?
Ask for its trade licence number and check it with the issuing authority or the UAE National Economic Register, make sure the licence covers car trading or rental and matches the name on the contract, and see the exact car and its VIN before paying anything.
Who owns a leased car in Dubai during the contract?
On a rental-style lease and on lease-to-own, the leasing company owns the car and it is registered in its name. On a bank loan the car is registered to you with the bank's mortgage on it. On our lease-to-own plans the car moves to your name after the last payment, or earlier if you settle in full.
What should I check with a luxury car leasing company?
The same things, with more care, because the numbers are larger. At 20% down the cash on day one is about a quarter of the price, as the annual payment is 5% of it. Ask about GCC specification, accident and service history and the insurance excess, and check that the mileage and usage rules fit how you drive.
Can I end a car lease early in Dubai?
It depends on the product. Rental-style leases often charge part or all of the remaining rentals, so ask for the cost at months 6, 12 and 24 as numbers. With us you can settle a lease-to-own contract at any time with no early-settlement penalty, and the car transfers to your name once it is paid in full.
Can I take a leased car to Oman?
No. Leaving the UAE is not permitted on our lease: a car you do not own outright needs a no-objection certificate from its legal owner to cross a border, and its insurance must extend to the other country.
Ready to Get Started?
Apply today — decision within 24 hours, no credit check, transparent pricing.
See Cars With Monthly Payments