Drive on Lease Meaning in the UAE: Lease, Rent or Lease to Own?
One word covers four different contracts. Here is how to tell which one an ad is offering, who owns the car while you pay, and what you are left with at the end.
What does "drive on lease" mean?
"Drive on lease" means driving a car someone else owns, for a fixed term and a monthly payment. In the UAE it usually means an operating lease: the dealer or leasing company keeps the car in its name, bundles in insurance, registration and servicing, and takes it back at the end. Without a purchase option, it never becomes yours.
That answer fits most ads, but in the UAE the word "lease" is stretched over four contracts: a monthly rental, an operating lease, a bank car loan and lease to own. Their monthly figures can look alike and their endings are completely different. "Car on lease" is used just as loosely: plenty of residents say their car is "on lease" when they are paying off a bank, and plenty of rental firms call a 12-month rental a lease. The phrase tells you little; the contract tells you everything, and this guide shows which lines to read.
Two notes. If you met the phrase in a driver job or ride-hailing context, that arrangement is between a driver and a transport operator and has its own rules; this guide is about cars for personal use. And we are a lease-to-own company in Dubai, so we have a side. We describe the other products the way their providers and the authorities do, with sources at the end, and say where ours is the wrong choice.
Where the phrase comes from: Toyota and Lexus "Drive-on Lease"
The phrase is also a product name: Al-Futtaim's Toyota and Lexus showrooms in the UAE have marketed their leasing programmes as "Drive-on Lease".
Toyota UAE's programme page, as archived in April 2026, described an all-inclusive monthly payment covering servicing and maintenance, comprehensive insurance and repairs, annual registration, handling of fines and tolls, breakdown recovery and passenger accident cover. You chose a 24- or 36-month contract, agreed a maximum annual mileage (the page offered 40,000 to 120,000 km) and made an upfront payment. At the end you could return the car with no further obligation or replace it with a new lease. Buying it was not one of the options.
The Lexus version, archived in July 2025, advertised monthly payments from AED 2,500 and down payments from 5%, and listed an option to purchase the vehicle. In December 2025 Toyota advertised a Land Cruiser on Drive-on Lease from AED 2,999 a month, with two years of free service, insurance and registration.
Three things follow, and they hold for most operating leases:
- The monthly pays for using the car, not for the car. That is why it can look low for the model: the lessor expects the car back and sells it on.
- The extras run for a set period. "Two years free" on a three-year contract means the third year is on you.
- Ownership is an option at best. Where a purchase option exists, its price and the window to use it are set in the contract. Get both in writing.
By 1 November 2026 those offer pages redirected to each brand's general offers page, so ask the showroom what it offers today.
Rent, operating lease, bank car loan or lease to own: side by side
The four contracts people call "lease" in the UAE, compared on the questions that decide what you get. The bank lines describe how UAE banks work in general; the last line in each group is our lease to own. This compares what each contract is; our Lease vs Rent vs Buy guide works out what each costs over one and three years.
Who owns the car during the term
- Monthly rental: the rental company.
- Operating lease, including dealer "drive on lease" programmes: the lessor or dealer.
- Bank car loan: you. The car is registered in your name, and the bank holds a mortgage over it until the debt is cleared.
- Lease to own with us: Drive Your Dream. The car stays registered to us for the whole term.
What the monthly pays for
- Monthly rental: use of the car, usually with insurance and registration included.
- Operating lease: use of the car, often with servicing, insurance and registration bundled in.
- Bank car loan: the car itself. Insurance and registration are yours to buy every year.
- Lease to own with us: the car itself, GPS tracking and our administration. Comprehensive insurance and RTA registration are one separate annual payment of 5% of the car's price, minimum AED 8,000. Servicing is yours.
Mileage
- Monthly rental and operating lease: a kilometre cap, with a charge for every kilometre over it.
- Bank car loan: no cap, because the car is yours.
- Lease to own with us: 25,000 km a year as standard, and AED 10 for each kilometre over it. If you drive more, 35,000 and 50,000 km packages work out cheaper per kilometre.
What you need to apply
- Monthly rental: a driving licence and a deposit or card block.
- Operating lease: often income documents and a credit bureau check, depending on the lessor.
- Bank car loan: under UAE Central Bank rules the bank can lend at most 80% of the car's value, over at most 60 months, with a monthly deduction of no more than half your salary. Banks also check your AECB report.
- Lease to own with us: your Emirates ID and your UAE driving licence. No salary certificate, no bank statements, no AECB check. A decision usually comes within 24 hours, and we still decline some applications.
Who owns a car on lease in Dubai? Check the mulkiya
The fastest test is to ask whose name will be on the mulkiya, the vehicle ownership card issued when a car is registered.
- Your name, with a bank's mortgage recorded against the car: a bank car loan. The car is yours, but before it can be transferred the RTA requires the mortgage to be released, which the bank does once the debt is settled.
- The leasing company's or the dealer's name: an operating lease, a rental or lease to own. On the card the three look identical; only the contract says whether the car goes back or transfers to you.
- A bank's name, under an Islamic Ijarah plan: the bank owns the car and leases it to you, and most vehicle Ijarah plans in the UAE end with ownership passing to you. Our guide to Islamic car finance compares it with Murabaha.
Registration to someone else has practical effects. The registered owner decides how the car may be used, and the insurance is written around that. On our lease the car stays in the UAE, and off-road and desert driving, track days and timed events are not allowed, because standard UAE comprehensive policies commonly exclude them. Towing a trailer or a boat is allowed with the right licence category if you tell us first, because it can add to the insurance cost. Renewals are not your job: we renew the registration and insurance every year from the annual payment.
What happens at the end of the term?
This is what separates the products, and it is what most ads leave out.
- Monthly rental: the car goes back. You settle fines, tolls and damage, and the deposit is returned once they clear.
- Operating lease: the car goes back for an inspection against the contract's wear-and-tear standard. You pay for excess kilometres and damage, then walk away or start a new lease. A purchase option, if there is one, names a price and a window; miss the window and it may lapse.
- Bank car loan: after the last payment you request a release and the bank has the mortgage lifted at the RTA. Emirates NBD, for example, says it processes the request within 3 working days.
- Lease to own with us: after your last monthly payment nothing more is owed for the car. We start the RTA transfer, handle the paperwork and the transfer fees, and the car is registered in your name, usually within 5 to 7 business days.
Before you sign any of these, check one more clause.
Early settlement. What it costs to finish early. Operating leases often charge a share of the unused months. On our lease you can settle at any time with no early-settlement penalty, and the car transfers once the contract is paid in full.
How to tell which one an ad is offering
Ads rarely name the product. These words give it away:
- "Return or replace", "upgrade every two years", "all-inclusive", a kilometre allowance: an operating lease. You are paying for use.
- "Option to purchase": an operating lease with a purchase option. Get the price and the dates you can use it in writing.
- "20% down payment", "salary transfer", "minimum salary", "AECB": a bank or finance-company product. A licensed bank or finance company must give you a Key Facts Statement before you sign, and you sign to confirm you received it. Read it first.
- "Lease to own", "rent to own": ownership is the point, but details vary between providers. Ask the four questions below.
- A monthly far below similar cars elsewhere: usually a large upfront payment or a car you hand back. Find out which.
Whatever the ad says, four questions sort it out in one message:
1. Whose name is on the mulkiya during the contract, and after the last payment?
2. Is any amount due at the end, and how much?
3. What exactly does the monthly cover, and for how many years?
4. How many kilometres a year are included, and what does each extra one cost?
Ask for the answers in writing. Our written offer sets out the down payment, the monthly, the number of monthly payments and the annual payment for each plan.
What our clients actually ask
Between 25 September and 1 November 2026 our team and our chat assistant left notes on 393 client conversations. We searched them by keyword for questions about how a contract ends, read every match and counted each client once, with no names or phone numbers attached. In at least ten the client asked some version of the same thing: what is due on the last day, whether every payment counts towards owning the car, and who pays for the transfer. Sixteen asked about the mileage limit. Two wanted the opposite of what we sell, cars they could hand back with no ownership, which is a rental or an operating lease.
The ending is the part an ad's headline leaves out, so it is the part people ask about. Our answers:
- What is due at the end? Nothing for the car. The last monthly payment is the last payment.
- Does every payment count? Yes. The down payment is payment number one, so a 36-month contract has 35 monthly payments after it. With zero down, all 36 are monthly payments.
- Who pays for the transfer? We handle the RTA transfer and its fees.
- Can I hand the car back instead? Lease to own is built around you keeping the car. If you want one you return, a rental or an operating lease is the honest answer, and we will say so.
A real lease-to-own plan, worked through
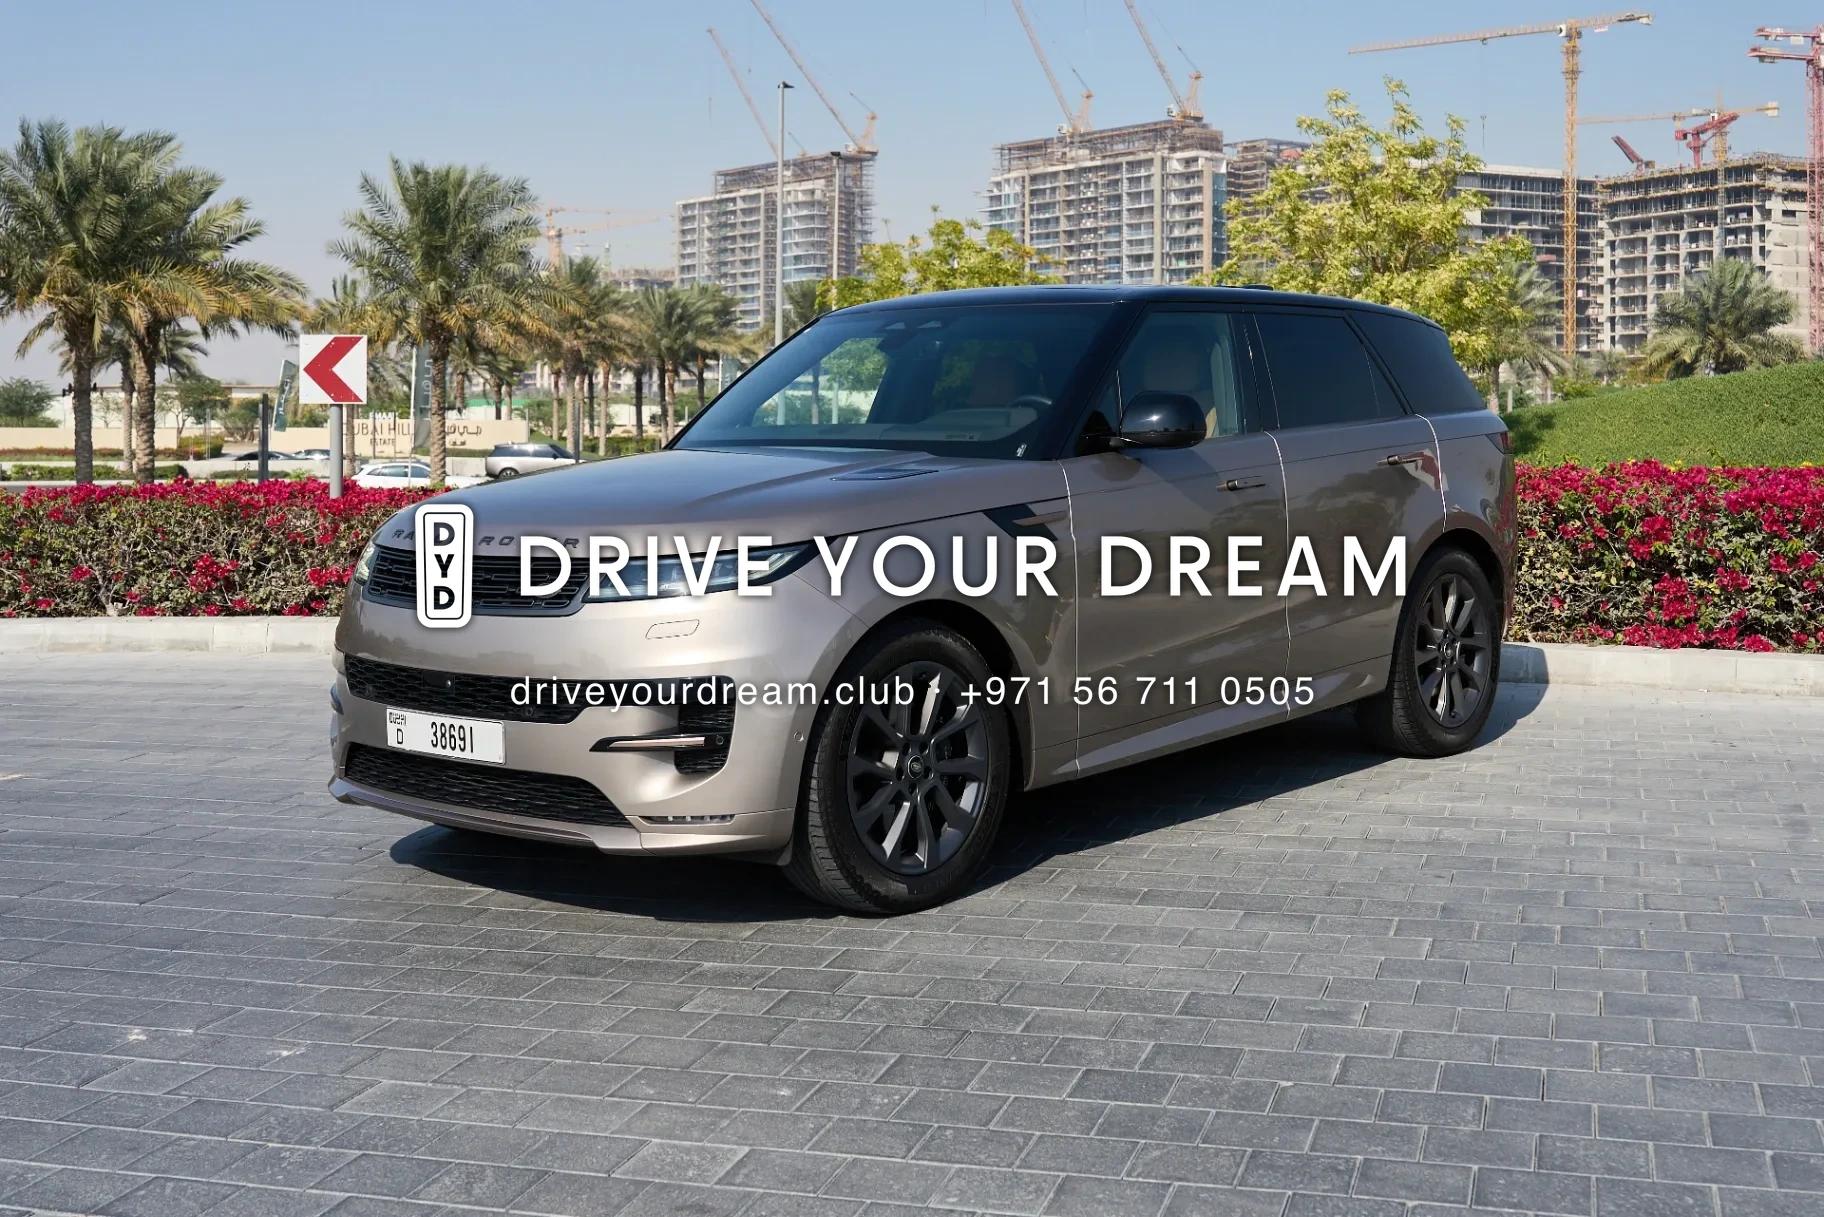
Here is how we price a car from our fleet: a 2023 Range Rover Sport listed at AED 315,000, with figures as of 1 November 2026. The payment is calculated once, on the amount left after your down payment, and fixed on the day you sign; nothing compounds. On top comes the annual payment for insurance and registration, AED 15,750 on this car (5% of its price), once in each contract year.
20% down over 36 months
- Payment number one, the down payment: AED 63,000
- Then 35 monthly payments of AED 12,384
- Due on the day you collect the car: AED 78,750, the down payment plus the first annual payment
- At the end: nothing further for the car, which transfers to your name
Zero down over 36 months, which this car offers
- 36 monthly payments of AED 15,050
- Due on day one: AED 30,800, the first monthly payment plus the first annual payment
20% down over 24 months
- AED 63,000 down, then 23 monthly payments of AED 16,216
- The same AED 78,750 on day one, and two annual payments instead of three
An operating lease on a similar car would show a lower monthly, because the lessor keeps the car and its resale value. Ours is higher because you are paying for the car itself, and at the end you own it.
Zero down is available on selected cars in our fleet, over 12, 24 or 36 months depending on the car; others start from 20% down. Prices move with the fleet, so check the live figure on the car's page or in our calculator.
The car in this example, with its live figure
Live from our fleet; the plans for this car are worked through above. Insurance, RTA registration and admin come as one annual payment.
Glossary: the words in a UAE lease contract
- Annual payment: on our lease, one payment a year of 5% of the car's price, minimum AED 8,000, for comprehensive insurance and RTA registration. On other contracts these may sit inside the monthly or be yours to arrange.
- Down payment or advance payment: what you pay at the start. With a bank it is at least 20%, because the bank can lend at most 80% of the car's value.
- Mulkiya: the vehicle ownership card issued at registration. It shows who owns the car; a bank's mortgage stays recorded against the car until it is released.
- Mortgage release: the step that removes a bank's claim on a car once the debt is paid. It must happen before the car can be transferred.
- Kilometre allowance: the distance included in the contract. Every kilometre over it is charged.
- Salik and Darb: the road toll systems of Dubai and Abu Dhabi. On our lease tolls are yours to pay; we supply the Salik tag and you keep it topped up.
- NOC: a no-objection certificate from a car's legal owner, needed for things such as crossing a border. On our lease the car is not allowed to leave the UAE.
- Key Facts Statement: the summary a licensed bank or finance company must give you before you sign up for one of its products.
If you want to own the car at the end
If your answer to "do I want to own this car in three years?" is yes, an operating lease is the wrong product however low its monthly looks, and the choice is between a bank and lease to own.
- A bank suits you if you qualify, have 20% to put down and are comfortable adding a new line to your AECB file. If you qualify, it is usually the cheapest way to own a car.
- Lease to own suits you if you would rather not go through a bank: you are new to the UAE, self-employed, have just changed jobs, or prefer two documents to a stack of them. Our How Leasing Works page walks through the process step by step.
- Neither suits you if you need a car for less than a year. Rent; our short-term lease guide compares monthly rental with a 12-month commitment.
Not in our fleet? Bring Your Own. If the car you want is listed on Dubizzle or at a dealer, our Bring Your Own programme can buy it and lease it to you. It takes cars listed from AED 150,000, model year 2023 or newer, not a Chinese brand and not fully electric (hybrids are fine), once the car passes our checks. Plans run from 20% down over 12 or 24 months (36 months only case by case), priced on the listing plus 5% VAT, and the car is yours after the last monthly payment. An AED 150,000 listing works out from about AED 8,100 a month over 24 months, with about AED 39,500 due at the start.
How we checked
Checked on 1 November 2026, and every source below opened on that date. Dealer offer pages change often, so for the Toyota and Lexus programmes we cite archived copies, which show how each product was described on the date given; the live addresses now redirect to each brand's general offers page.
Our own figures come from the fleet price list on 1 November 2026 and the same calculator that produces our written offers. The client-question counts come from the notes our team and chat assistant left on client conversations between 25 September and 1 November 2026, searched by keyword, read one by one and counted once per client, without names or phone numbers.
Our terms can change, and every plan is subject to DYD confirming the application and the car.
Sources
- Drive-on Lease programme (archived 16 April 2026), Toyota UAE
- Drive-on Lease Land Cruiser offer (archived 22 December 2025), Toyota UAE
- Drive-on Lease programme (archived 7 July 2025), Lexus UAE
- Getting a car loan: up to 80% of the car's value, up to 60 months, a mortgage over the car, UAE Government portal u.ae
- Registering vehicles: the vehicle ownership card (mulkiya), UAE Government portal u.ae
- Apply for Changing a Vehicle Ownership: a mortgaged car must be released first, Roads and Transport Authority (RTA), Dubai
- Consumer Protection Standards, clauses 2.1.1.19–2.1.1.20: the Key Facts Statement (PDF), Central Bank of the UAE
- Auto Loan Release Request: how a bank releases a car mortgage, Emirates NBD
Frequently Asked Questions
What is drive on lease?
Drive on lease means driving a car someone else owns, for a fixed term and a monthly payment. In the UAE it usually describes an operating lease: the dealer or lessor keeps the car, often bundles insurance, registration and servicing, and takes it back at the end. On its own it does not mean the car becomes yours.
What does car on lease mean in the UAE?
It is everyday shorthand for a car paid for monthly, used for four different contracts: a monthly rental, an operating lease, a bank car loan and lease to own. To tell them apart, ask whose name is on the mulkiya during the contract and what happens after the last payment.
Is drive on lease the same as renting a car?
Close, but not the same. A monthly rental can usually be stopped at short notice. An operating lease commits you to a fixed term, typically 24 or 36 months, with a kilometre allowance and a charge for ending early. In both cases the car goes back at the end and you have nothing to sell.
Who owns a car on lease in Dubai?
On a rental, an operating lease or lease to own, the leasing company owns the car and it is registered in its name. On a bank car loan you own the car, but the bank holds a mortgage over it until the debt is cleared. With Drive Your Dream the car stays registered to us for the term and transfers to you after the last payment.
Can I buy the car at the end of a drive on lease contract?
Only if the contract gives you a purchase option. Toyota UAE's Drive-on Lease page, as archived in April 2026, offered return or replace at the end, while the Lexus version listed an option to purchase. Where an option exists, get the purchase price and the window to use it in writing before you sign.
Is a car on lease the same as a bank car loan?
No. With a bank car loan the car is in your name from day one and the bank holds a mortgage over it; UAE rules cap such a loan at 80% of the car's value and 60 months. With an operating lease the lessor owns the car and takes it back. With lease to own the lessor owns it until the contract is complete, then it becomes yours.
What happens at the end of a lease-to-own contract with Drive Your Dream?
After your last monthly payment, nothing more is owed for the car: we start the RTA transfer, handle the paperwork and the transfer fees, and the car is registered in your name, usually within 5 to 7 business days. You can also settle early at any time with no early-settlement penalty.
What do I need to lease a car to own with Drive Your Dream?
Your Emirates ID and your UAE driving licence. We do not ask for a salary certificate, bank statements or an AECB report. A decision usually comes within 24 hours, we still decline some applications, and on a car from our fleet the keys usually follow within 1 to 3 business days.
Ready to Get Started?
Apply today — decision within 24 hours, no credit check, transparent pricing.
See How Lease to Own Works